Acquisition coverage is written from the owner’s chair: the negotiation, the wire, the champagne. But most of the people affected by your deal never saw a term sheet, and their version of the story starts the morning after the announcement, at a help desk, mid-queue, wondering whether direct deposit still works. This post is the deal from that chair: what the first 90 days actually feel like for a tech or an account manager, and, for the seller choosing between buyers, what separates the acquirers whose teams settle from the ones whose teams scatter.
Week one: the announcement and the physics of silence
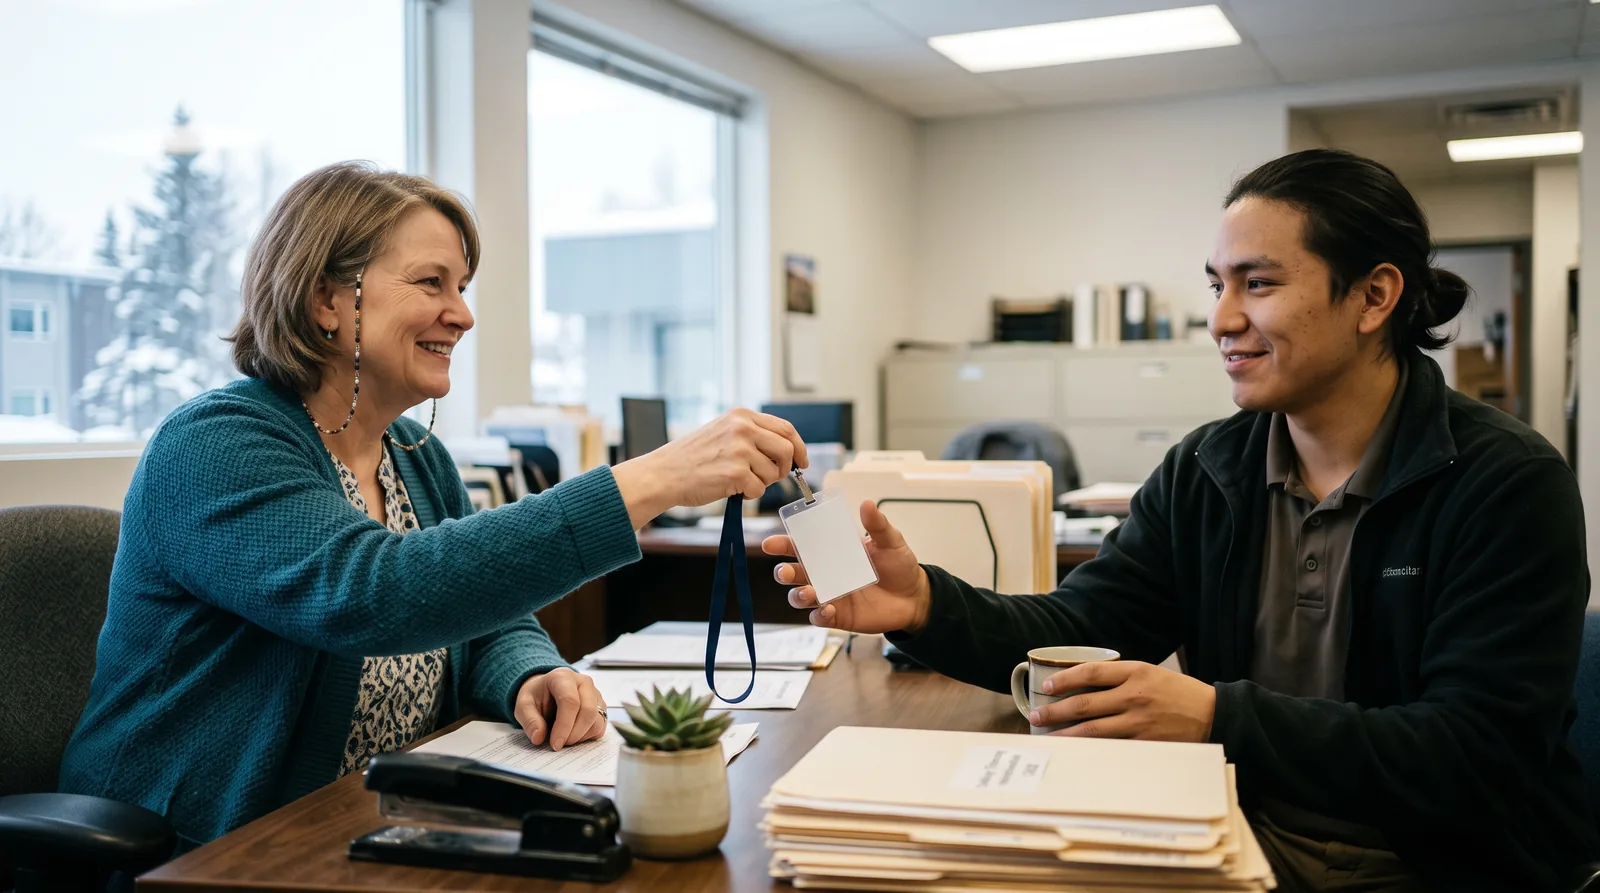
The all-hands lands, the new owners say warm things, and then everyone goes back to their desks and does exactly one thing: they check whether their specific world is okay. Paycheck, insurance, manager, seat. In a well-run close, those answers arrived with the announcement, because offers went out before closing and day one includes a personal, individual conversation: here’s your role, your pay, your benefits mapping, your manager, in writing. In a badly-run one, the answers are “details coming soon,” and the team spends week one manufacturing answers from fragments, which is how a delayed benefits FAQ becomes “I heard they’re gutting the plan” by Thursday.
The tell, from the team’s side, is specificity. Vague warmth (“nothing changes, we’re excited about the family we’re joining”) actually raises anxiety, because everyone over 25 has heard it before. Specific mundane facts (“payroll stays on the 15th and 30th, same insurance through January 1, then the new plan, here’s the comparison sheet”) lower it. Good acquirers front-load the boring. The boring is the message.
Weeks two through six: the small frictions
Then comes the era of little things, and the little things carry disproportionate weight because they’re what the day is made of. The expense report goes to a new system. The purchasing card has a new approval chain, and the tech who used to grab a hard drive off the shelf now waits two days. Someone’s email signature changes before they were told it would. The new HR portal wants everyone to re-enroll in benefits during a service outage week. None of this is malice; it’s the administrative integration every deal requires. What distinguishes acquirers is whether someone owns the friction: a named integration lead, reachable, empowered to fix the purchasing-card problem in a day, versus a distant shared-services inbox that answers in ticket numbers.
For account managers, this stretch has a specific flavor: clients call them asking what the sale means, and if the company hasn’t armed them with real answers, they improvise or deflect, and both feel terrible. Good acquirers treat client-facing staff as the transition’s front line and brief them like it: talking points, an FAQ that’s actually honest, and a rule that no client-facing person should ever learn news from a client.
Weeks six through twelve: the real answers arrive
By month two or three, the questions stop being administrative and start being structural, and the team reads the answers like tea leaves. Does the new manager actually listen in one-on-ones, or is the meeting a status ritual? When the first tool consolidation gets announced (and one will; every acquirer consolidates something), is it presented with reasons and a realistic timeline, or does it land as a Friday email? When the first person quits (and one will; every transition loses someone), is the departure handled gracefully and the workload rebalanced, or does it just spread across the survivors?
This is also when the difference between buyer models becomes visible on the floor, exactly as the roll-up mechanics predict. A consolidator’s 90-day plan converges the acquired shop toward platform standard: centralized dispatch, new metrics on the wall, the first pricing letters. An operator’s 90-day plan (ours, and we’ve run it) converges the other direction: keep the service model that made the business worth buying, change the back office where nobody’s client feels it, and defer every optional disruption until the team trusts the mandatory ones. Neither approach is secret. From the team’s chairs, they just feel like completely different acquisitions.
What the seller controls
If you’re the owner reading this pre-sale, the actionable part: everything above was determined before closing, by three things you controlled. The buyer you picked, whose economics predicted the 90-day plan. The terms you negotiated, which decided whether offers, comp floors, and retention money existed. And the transition you personally ran, because for the first 90 days you are the credibility bridge: present, visible, saying true things, taking the temperature and reporting it to the new owners while they still listen with acquisition-grade attention. Owners who ghost at close (contractually free, emotionally understandable) remove the one person the team was going to believe.
Ask any buyer, us included, to walk you through their last acquisition’s first 90 days from a technician’s point of view: what changed, in what order, announced how, and who quit. The ones who can answer in specifics have done it deliberately. The ones who answer in adjectives are telling you the team’s experience is an afterthought, and your people will live in that afterthought. It’s laid out, week by week, on our after the sale page, and the sellers we’ve closed with will describe how it actually went. That’s the standard worth demanding from everyone at your table.