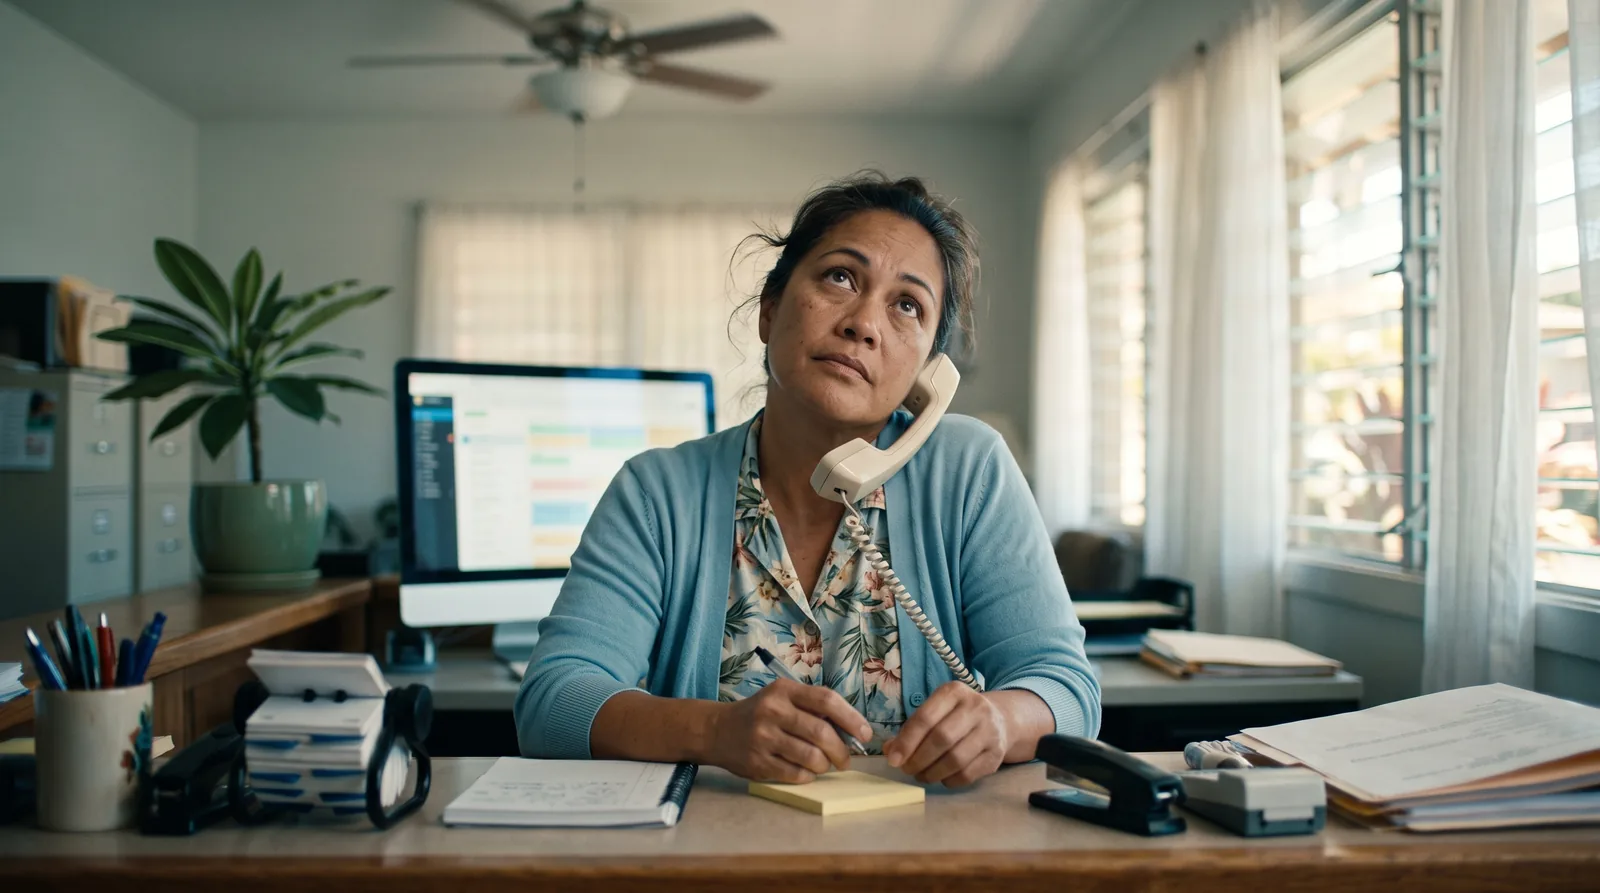
Meet the office manager at a 40-person engineering firm. Call her Dana. She’s been your client’s day-to-day contact for nine years, she has your dispatcher’s direct line memorized, and when the announcement email about your acquisition lands in her inbox, she does not think about multiples or synergies. She forwards it to her boss with one line: “Should we be worried?” Then she starts watching.
This post is written for sellers, but it lives behind Dana’s eyes, because your client base’s durability after a sale is just thousands of Dana-moments aggregated, and she’s watching for five specific things. Buyers know this list. You should too, because it’s also the list of commitments you can demand from whoever buys you.
She’s watching the phone. The first time something breaks after the announcement is the referendum. Does the same dispatcher answer? Does the tech who shows up know that the CAD workstations are sacred during deadline weeks and the server closet key lives with facilities? Or does she reach a new queue, in a new accent of corporate politeness, where she’s asked to describe her environment to someone reading it off a screen for the first time? Dana can absorb one clumsy call and will forgive it. A pattern of them, in the first quarter, and her boss gets a different one-liner: “I think we should look around.” This is the local-continuity math experienced from the other side of the counter, one ticket at a time.
She’s watching the paper. A few months in, an envelope arrives: new master agreement, new entity name, “updated terms to reflect our combined capabilities.” Dana reads contracts for a living, more or less, and she notices what moved: the SLA got vaguer, the auto-renewal got longer, the termination clause got harder, and there’s a new schedule of fees for things that used to just happen. Re-papering is sometimes legitimate (asset deals require it), and clients understand that. What they’re reading for is direction: paper that preserves their deal signals stewardship, and paper that quietly worsens it signals what the new owner thinks the relationship is for.
She’s watching the invoice. Every acquired client expects a price increase; Dana’s boss literally budgeted for one the day the announcement came. What they’re watching is size, timing, and manners. A reasonable adjustment, communicated in advance, tied to visible service (the new security stack, the upgraded backup platform), lands fine, because your prices were probably below market anyway. The other version, the 20-to-40% “harmonization” letter in month eight, effective in thirty days, take it or leave it, is the platform playbook executing on schedule, and it converts even loyal Danas into RFP-writers, because the letter’s message isn’t the number. It’s that nobody in the new company fears losing her.
She’s watching the faces. The account manager who did her quarterly reviews, the two engineers who know the building: are they still there in month six? Dana reads staff departures the way sailors read barometers, and she’s right to, because the techs leave before the service degrades, not after. One familiar departure is life. Three is a forecast.
She’s watching you. The seller personally. Did you call before the announcement or did she learn from the email blast? Are you visible during the transition, vouching with your presence, or did you vanish the day the wire cleared? Dana has trusted your judgment for nine years, and she’s willing to extend that trust to your successor exactly once, on your say-so. Owners underestimate this lever more than any other: your engaged, specific, personal endorsement, in the room, is worth more retention than any clause in the announcement letter.
Now flip the lens back to the seller’s chair, because every watched thing above is negotiable before closing. You can require a transition plan that keeps the local dispatch number and named contacts for a defined period. You can review the re-papering templates before they go out under a brand you built. You can negotiate constraints or notice requirements around pricing changes to the acquired base during the transition window. You can secure the retention of the client-facing people whose faces are the product. And you can commit your own time to the top-account calls, priced into the deal as the transition services they genuinely are.
A buyer’s reaction to this list is itself diligence. The ones who intend continuity will negotiate specifics happily, because you’re asking them to write down their own plan. The ones who hedge every item (“we can’t constrain future business decisions”) have answered a different question honestly, and you should hear it. Our own answers are standing ones, on the record: the phone, the faces, the paper, and the manners around pricing are most of what we think we’re buying, and we’ll put each in writing, deal by deal, next to everything else we commit to.
Dana, for what it’s worth, is watchable in reverse. Sellers sometimes ask us how they’ll know a transition is going well, months after close, from outside. The answer: her renewal. Clients who felt the handoff vote quietly, at term’s end, and a base that re-signs through an ownership change is the only five-star review this industry issues. It’s the one we run our integrations for, and the one your deal terms should be built to earn.